October 1, 2026

We use cookies on this site to improve the user experience and analyze website traffic. To learn more about how we use cookies, please see our Manage Cookies page. You can adjust your cookie settings to allow only specific types of cookies. By continuing to use our site, you are agreeing to our Privacy Policy and cookies usage.
Economic Outlook
The Atlanta Fed GDPNow model currently estimates third-quarter real GDP growth of 3.7% (versus consensus of 2.6%), revised from 4.8% one month ago. The Conference Board Leading Economic Index declined 0.1% in August to 99.5. The ISM Manufacturing PMI registered 54.5 in September, down from 54.6 in August but marking the ninth consecutive month of expansion in manufacturing activity. Consumer sentiment fell sharply in September, with the University of Michigan Consumer Sentiment Index posting a final reading of 48.1. The NAHB Housing Market Index declined three points to 32 in September, with the ‘Expected Sales of Single‑Family Homes for the Next Six Months’ subcomponent falling six points to 37. The 5-year breakeven inflation rate was 2.36% at the end of September, up slightly from 2.31% at the end of August. The average interest rate for a 30-year fixed-rate mortgage was approximately 7.28% as of October 1.
Fixed Income
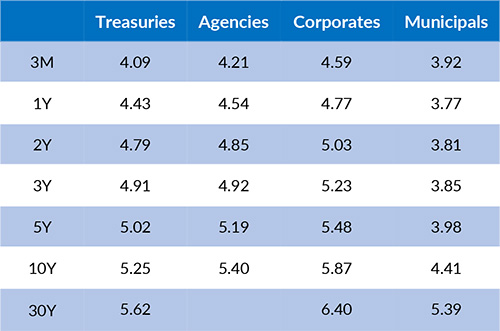
The Federal Reserve raised the federal funds target range by 25 basis points to 3.75%-4.00% at its September meeting. The decision was unanimous and represented the first increase in the federal funds rate since July 2023. The Federal Reserve’s updated projections showed an additional 25 basis points of tightening through year-end, with 16 officials expecting at least one more increase in 2026. Amid surging yields in recent sessions, the 2-year Treasury yield ended September at 4.87%, while the 10-year and 30-year Treasury yields finished the month at 5.27% and 5.62%, respectively. The 10-year and 30-year Treasury yields reached their highest levels since 2002, while the Treasury yield curve remained positively sloped at month-end. Credit spreads diverged by credit quality, with spreads on bonds rated CCC or lower reaching the 80th percentile over the past 30 years, compared with limited movement in investment-grade spreads. Much of the recent increase in longer-term Treasury yields is a result of higher real yields, while market-based inflation expectations remained comparatively stable.
Yield Curve
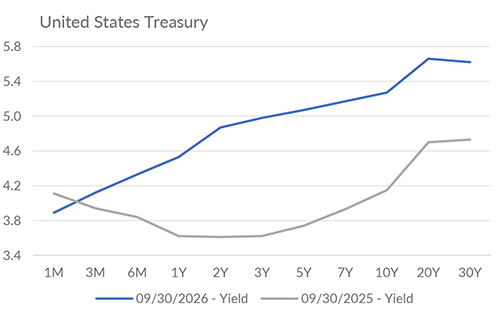
Current Generic Bond Yields
Equities
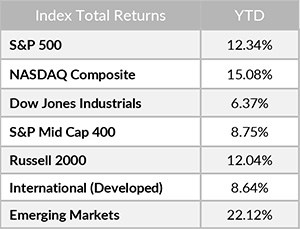
U.S. equity markets ended September near record levels, although market participation narrowed during the month. While the S&P 500 index was nearly unchanged in September, the equal-weight S&P 500 index declined by 5.2%. Fewer than 25% of S&P 500 constituents traded above their 50-day moving average at month-end. Meanwhile, third-quarter earnings growth estimates remain near 29%, with all 11 sectors expected to report positive year-over-year earnings growth. The S&P 500 currently trades at approximately 19.2 times forward earnings, modestly below its five-year average.
In 2026, the best performing U.S. sectors have been Energy (+40.28%), Information Technology (+28.38%), and Health Care (+10.15%). The worst performing sectors have been Consumer Discretionary (-5.82%), Utilities (-5.65%), and Financials (-1.30%). On a total return basis, the Russell 1000 Growth Index returned 5.83% year to date, while the Russell 1000 Value Index increased 17.26% over the same period.
{"dialogBean":{"articleAbstract":"The Atlanta Fed GDPNow model currently estimates third-quarter real GDP growth of 3.7%.","priority":"1","isFeatured":"false","isNews":"false","hideInBlogLanding":"false","trustmarkDate":"October 01, 2026","trustmarkExpirationDate":"October 06, 2026","authorBean":{"authorName":"Alex Essary","profilePicPath":"/content/dam/trustmark/associates/ef/alex-essary_sm.jpg"}},"pageTitle":"Portfolio Manager Commentary - October 1, 2026","pageThumbnail":"/content/dam/trustmark/advice/commentary/Portfolio-Manager-Commentary_th.jpg","pageTags":["trustmark:investment-management"],"pageTagTitles":["Investment Management"],"pageName":"01-portfolio-manager-commentary","pagePath":"/content/trustmark/trustmark/advice/2026/10/01-portfolio-manager-commentary","externalPagePath":"https://www.trustmark.com/advice/2026/10/01-portfolio-manager-commentary.html","fbAppId":"662611918413208","positioningBean":[{"layout":"small"},{"layout":"large-horizontal"},{"layout":"large-vertical"}]}
Related Articles
September 15, 2026
The ISM Services PMI increased to 55.4 in August from 54.1 in July, reaching its highest level in six months.
August 15, 2026
In July, the ISM Services PMI registered 54.1, marking the 25th consecutive month of expansion and highlighting the continued resilience of the U.S. services sector, which accounts for the majority of economic activity.