
August 15, 2026

We use cookies on this site to improve the user experience and analyze website traffic. To learn more about how we use cookies, please see our Manage Cookies page. You can adjust your cookie settings to allow only specific types of cookies. By continuing to use our site, you are agreeing to our Privacy Policy and cookies usage.

Economic Outlook
In July, the ISM Services PMI registered 54.1, marking the 25th consecutive month of expansion and highlighting the continued resilience of the U.S. services sector, which accounts for the majority of economic activity. The NFIB Small Business Optimism Index rose to its highest level of 2026, while the survey’s results showed that hiring plans reached their highest level since 2022. Labor market conditions were mixed during the month, as nonfarm payrolls declined by 23,000 while the unemployment rate improved slightly to 4.1%. Average hourly earnings increased 3.2% year-over-year, the slowest pace over the past 5 years. The annual inflation rate fell to 3.4% in July, while core inflation eased to 2.5%. Producer prices increased 4.7% year-over-year in July, the lowest reading since March. Consumer sentiment declined in August, with the University of Michigan Consumer Sentiment Index posting a preliminary reading of 51.0, down from 55.2 in July. The average interest rate for a 30-year fixed-rate mortgage was approximately 6.67% as of August 13.
Fixed Income
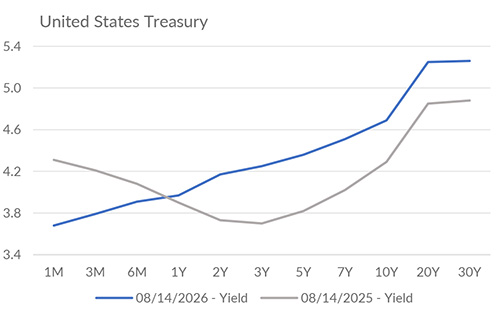
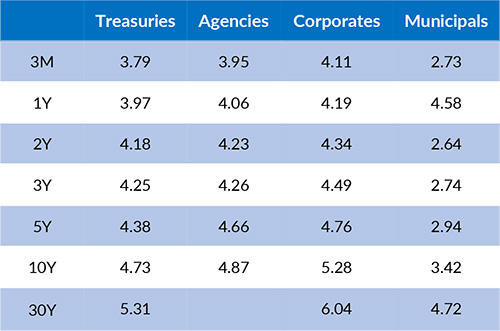
The federal funds target range remains at 3.50%-3.75%. Since the start of 2026, the Treasury yield curve has shifted higher despite no change in the federal funds rate. The 30-year Treasury yield is approximately 5.29%, near its highest level since 2007. Despite elevated yields across the curve, demand at several recent Treasury auctions has remained solid, suggesting investors continue to view current yields as attractive relative to levels available over much of the past decade. With three FOMC meetings remaining in 2026, expectations for additional policy tightening have gradually shifted lower, and futures markets currently assign a 67% probability that the federal funds target range remains unchanged at the September meeting.
Yield Curve
Current Generic Bond Yields
Equities
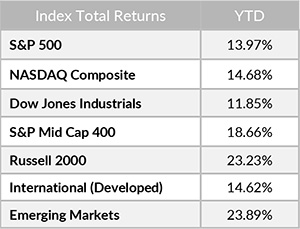
U.S. equities continued to advance during the first half of August, with the S&P 500 and NASDAQ Composite posting their third consecutive weekly gains. Second quarter earnings season has remained strong, with 88% of S&P 500 companies having reported results as of the latest FactSet update. Of those companies, 86% reported earnings above estimates, exceeding both the 5-year and 10-year averages. Small-cap and value-oriented stocks have continued to outperform growth stocks year to date. Market breadth for large-cap stocks remains strong, with more than 73% of S&P 500 constituents trading above their 200-day moving average on August 13, the highest share since 2024.
In 2026, the best performing U.S. sectors have been Energy (+39.94%), Information Technology (+24.30%), and Industrials (+20.93%). The worst performing sectors have been Consumer Discretionary (+0.89%), Communication Services (+1.70%), and Utilities (+5.23%). On a total return basis, the Russell 1000 Growth Index returned 5.96% year to date, while the Russell 1000 Value Index increased 21.85% over the same period.
{"dialogBean":{"articleAbstract":"In July, the ISM Services PMI registered 54.1, marking the 25th consecutive month of expansion and highlighting the continued resilience of the U.S.","priority":"1","isFeatured":"false","isNews":"false","hideInBlogLanding":"false","trustmarkDate":"August 15, 2026","trustmarkExpirationDate":"September 04, 2026","authorBean":{"authorName":"Alex Essary","profilePicPath":"/content/dam/trustmark/associates/ef/alex-essary_sm.jpg"}},"pageTitle":"Portfolio Manager Commentary - August 15, 2026","pageThumbnail":"/content/dam/trustmark/advice/commentary/Portfolio-Manager-Commentary_th.jpg","pageTags":["trustmark:investment-management"],"pageTagTitles":["Investment Management"],"pageName":"15-portfolio-manager-commentary","pagePath":"/content/trustmark/trustmark/advice/2026/8/15-portfolio-manager-commentary","externalPagePath":"https://www.trustmark.com/advice/2026/8/15-portfolio-manager-commentary.html","fbAppId":"662611918413208","positioningBean":[{"layout":"small"},{"layout":"large-horizontal"},{"layout":"large-vertical"}]}

Related Articles
August 1, 2026
The Atlanta Federal Reserve currently estimates real GDP growth of 6.2% for Q3 2026, well above the consensus estimate of approximately 2.0%.
July 15, 2026
In June, the ISM Services PMI registered 54.0, marking the 24th consecutive month of expansion for the services sector.
July 1, 2026
The Atlanta Fed GDPNow model currently estimates second quarter real GDP growth of 1.2%, down from 3.0% one month ago.